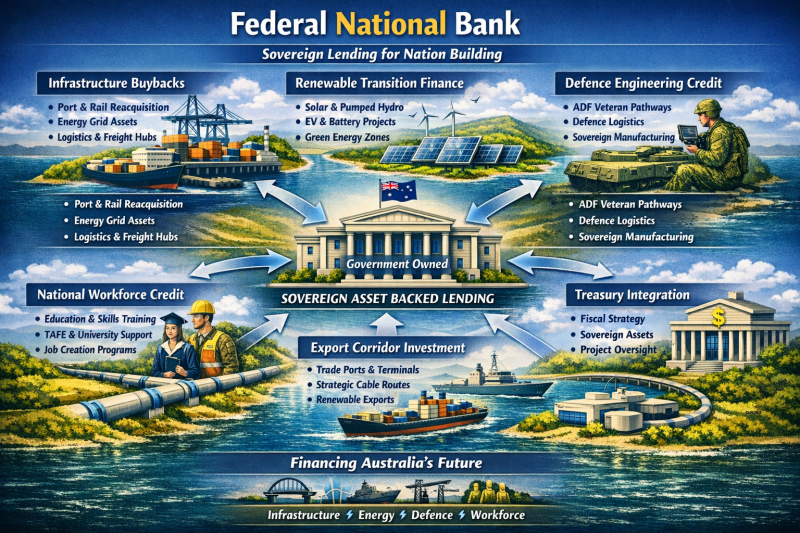
🏛️ National Government Bank (Federal Sovereign Lending Authority)
🔷 Purpose
A fully government-owned financial institution designed to:
-
Fund sovereign infrastructure buybacks
-
Finance strategic national projects
-
Support Defence, Energy, Transport, and Workforce reforms
-
Enable equity-based lending against sovereign assets
💡 Strategic Advantages
-
Asset-backed lending: No foreign debt exposure
-
Sovereign ownership retention: Assets remain Australian-owned
-
Project-tied bonds: Transparent, reform-aligned funding
-
Veteran & workforce uplift: Direct credit pathways for skilled transition
-
Grid stability & energy firming: Hydro and solar projects financed internally

1. Sovereign Lending Division
-
Issues low-interest loans backed by sovereign assets (ports, rail, energy grids)
-
Enables project-tied credit for national infrastructure and reform initiatives
-
Replaces foreign debt exposure with internal sovereign equity mechanisms

2. Infrastructure Buyback Unit
-
Finances reacquisition of:
-
Ports and shipping terminals
-
National rail corridors
-
Energy transmission infrastructure
-
Logistics hubs and freight networks
-
-
Supports staged buyback timeline with public ownership retention

3. Renewable Transition Finance
-
Funds:
-
Solar zone development
-
Pumped hydro reservoir construction
-
EV logistics and battery precincts
-
-
Enables long-duration energy storage and grid firming
-
Aligns with Indo-Pacific export corridor strategy
4. Defence Engineering Credit
-
Provides credit pathways for:
-
ADF veteran transition into sovereign engineering roles
-
Defence logistics precinct build-out
-
Sovereign manufacturing of EV platforms and battery systems
-
-
Supports Defence-led infrastructure and workforce reform
5. National Workforce Credit
-
Finances:
-
Education-to-employment pipelines
-
TAFE and university reform integration
-
Skilled job creation across portfolios
-
-
Enables direct credit access for students and transitioning workers
6. Export Corridor Investment
-
Backs infrastructure for:
-
Strategic cable routes
-
Indo-Pacific trade terminals
-
Renewable energy export zones
-
-
Aligns with national logistics and foreign policy objectives

7. Treasury Integration Office
-
Coordinates with Department of Finance to:
-
Value sovereign assets
-
Manage fiscal strategy
-
Oversee reform-linked credit issuance
-
-
Ensures transparency and accountability across all lending divisions
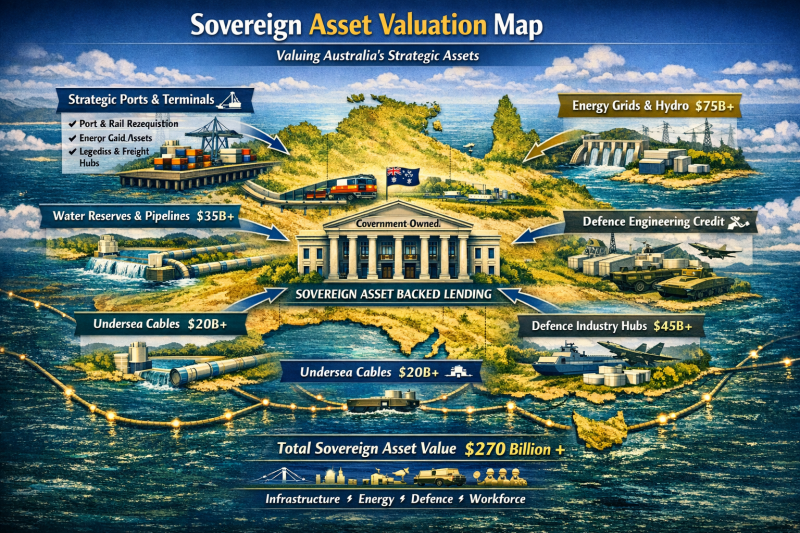
💰 Valuation Breakdown
-
Strategic Ports & Terminals — $40B+
-
Rail & Freight Network — $55B+
-
Energy Grids & Hydro — $75B+
-
Water Reserves & Pipelines — $35B+
-
Undersea Cables — $20B+
-
Defence Industry Hubs — $45B+
🏛️ Total Sovereign Asset Value
$270 Billion + — available for sovereign-backed lending, buyback financing, and reform-linked investment.
This map pairs perfectly with your Federal Bank schematic and can be used to justify lending capacity, project prioritisation, and national ownership logic.
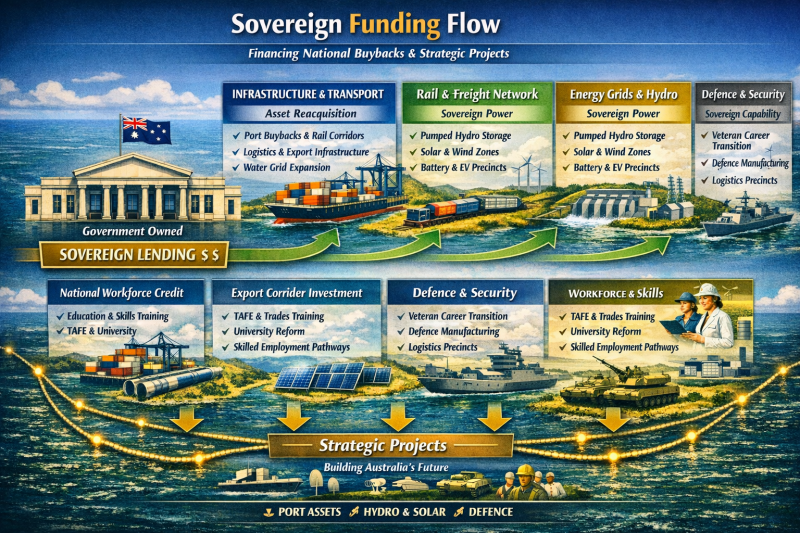
🧠 Strategic Recommendation for Australians Unified
To build your Federal National Bank, the smartest path is:
Option A — Build + Acquire Hybrid Model
-
Create the sovereign bank from scratch (clean governance, no legacy issues)
-
Acquire a small–medium ADI to instantly gain:
-
APRA licence
-
Branch network
-
Banking infrastructure
-
Customer base
-
-
Merge them into a national sovereign lending authority
This avoids:
-
Big Four restrictions
-
ACCC battles
-
Political backlash
And gives you:
-
Immediate operational capability
-
National footprint
-
Public trust
-
Full sovereign control
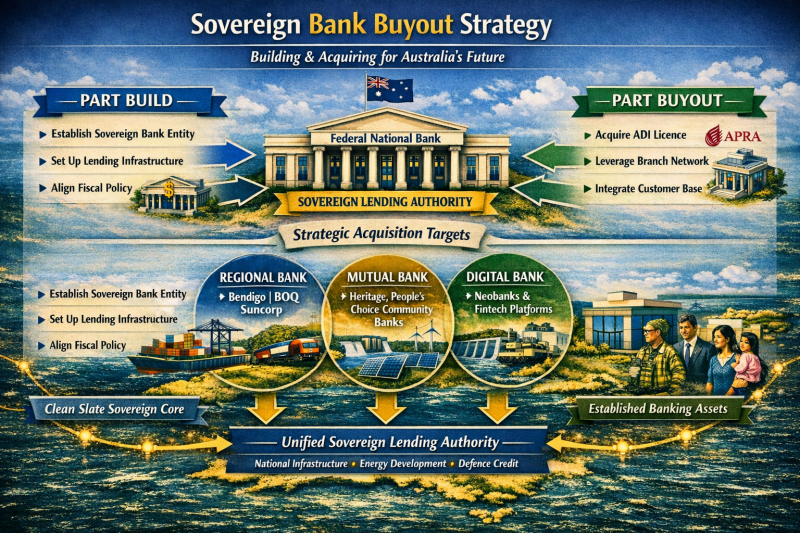
🏦 Sovereign Bank Buyout Strategy (Part Build + Part Buyout)
This is the exact hybrid model that gives you:
-
Clean sovereign control
-
Instant national banking capability
-
APRA licensing without delays
-
Branch networks + customer base
-
Digital banking infrastructure
It’s the fastest, safest, and most politically viable path to establishing a Federal National Bank.
🔷 PART BUILD — Your Sovereign Core
This is the “clean slate” foundation that ensures the bank is fully government-owned, transparent, and aligned with your reform portfolios.
What you build internally
-
Sovereign Bank Entity
-
Legally established under Commonwealth law
-
Treasury-aligned governance
-
-
Lending Infrastructure
-
Sovereign asset–backed credit engine
-
National project financing systems
-
-
Fiscal Policy Integration
-
Treasury + Finance oversight
-
Reform-linked lending rules
-
This gives you the sovereign authority and the policy engine.
🟩 PART BUYOUT — Your Operational Capability
This is where you acquire an existing ADI to instantly gain:
-
APRA licence
-
Branch network
-
Customer base
-
Banking systems
-
Payments infrastructure
Three viable acquisition categories
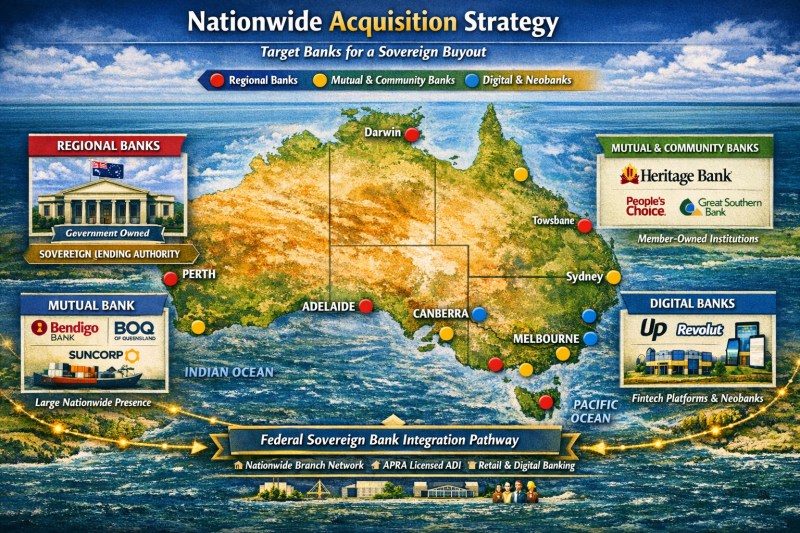
1. Regional Banks (High-value targets)
-
Bendigo & Adelaide Bank
-
Bank of Queensland (BOQ)
-
Suncorp Bank (if ANZ deal collapses)
Why: Large footprint, strong trust, scalable infrastructure.
2. Mutual / Customer-Owned Banks (Most achievable)
-
Heritage Bank
-
People’s Choice
-
Great Southern Bank
-
Beyond Bank
-
Newcastle Permanent
-
Teachers Mutual
-
Defence Bank
Why: Member-owned → easier acquisition pathway.
3. Digital Banks (Fastest integration)
-
Up Bank
-
Alex Bank
-
Revolut AU (local entity)
-
Other neobank platforms
Why: Modern systems, low overhead, instant digital capability.
🟡 Combined Outcome
Your map shows the final integration:
Unified Sovereign Lending Authority
Funding:
-
National Infrastructure
-
Energy Development
-
Defence Capability
-
Workforce & Skills
This is the engine that powers your entire Australians Unified reform program.

📆 Sovereign Bank Acquisition Timeline (2026–2029)
🔴 Regional Banks (Bendigo, BOQ, Suncorp)
-
Target Window: 2026–2027
-
Why First:
-
High-value targets
-
Large branch footprint
-
APRA licensed
-
Immediate national coverage
-
🟡 Mutual & Community Banks (Heritage, People’s Choice, Great Southern, Defence Bank)
-
Target Window: 2027–2028
-
Why Second:
-
Member-owned → easier acquisition
-
Strong community trust
-
Ideal for regional and Defence-linked expansion
-
🔵 Digital & Neobanks (Up Bank, Revolut AU, Alex Bank)
-
Target Window: 2026–2029
-
Why Flexible:
-
Fastest integration
-
Scalable digital infrastructure
-
Can be acquired early or layered in later
-
🏦 Sovereign Bank Branch Network Strategy
🔷 Phase 1: Acquisition-Based Branches
These are existing branches you gain instantly by acquiring regional or mutual banks.
Subtotal: ~800+ branches
These give you immediate national coverage across metro, regional, and Defence-linked zones.
🟩 Phase 2: Sovereign Build-Out
These are new branches you build in strategic locations aligned with your portfolios.
Suggested Build Locations:
-
National Infrastructure Corridors (ports, rail hubs)
-
Energy Zones (solar, hydro, battery precincts)
-
Defence Logistics Precincts
-
Workforce Transition Hubs (TAFE, university, job pipelines)
Estimated New Branches:
-
Metro Cities: 1–2 per capital city → ~16
-
Regional Growth Zones: 2–3 per state → ~24
-
Strategic Precincts: 1 per major reform site → ~30
Subtotal: ~70 new sovereign branches
🧮 Total Branch Network Estimate
Existing (Buyout): ~800 New (Build): ~70 Total: ~870 branches nationwide
🏛️ Sovereign Bank Buildout Timeline (2026–2029)
🔴 Phase 1: Acquire Regional Banks (2026–2027)
-
Targets: Bendigo Bank, BOQ, Suncorp
-
Purpose: Instant APRA licence, branch network, national footprint
🟡 Phase 2: Integrate Mutual Banks (2027–2028)
-
Targets: Heritage Bank, People’s Choice, Great Southern
-
Purpose: Community trust, Defence-linked access, regional coverage
🔵 Phase 3: Expand Digital & Neobanks (2026–2029)
-
Targets: Up Bank, Revolut AU, fintech platforms
-
Purpose: Scalable digital infrastructure, modern banking systems

